size/s: "Out-of-page"
size/s: "[[[970,250],[970,90],[728,90]],[[728,90]],[[320,50]]]"
This week Money asks Invast for a hot stock pick - McGrath (ASX:MEA)
Key statistics:
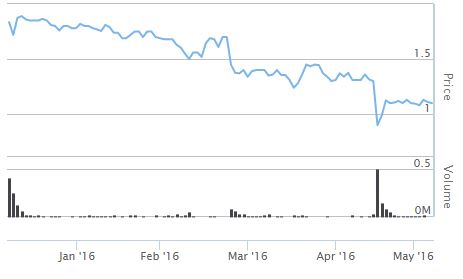
10/05/16 closing share price: $1.060 52 week high: $2.030 52 week Low: 0.857 Most recent dividend: - Annual dividend yield: - Franking: -
McGrath shares have been smashed since the initial public offering four months ago. We have no problem with the market response - there has been disappointment over earnings. But now is the time to sit back and have a mature look at the numbers.
The implied EV/EBITDA multiple (enterprise value divided by earnings before interest, tax, depreciation and amortisation) at $1.10 a share is around 5.5 times. Keep in mind that we are talking about a business that has net cash, no debt and transactional earnings that can fluctuate and cause disappointment.
The fact that McGrath is a listed entity with reasonably strong earnings means that it can go out and consolidate the residential real estate agency market. We see this as a potential national rollout story that needs to be carefully executed.
The market will be cautious but the valuation is compelling. The market loves a good growth story.
McGrath has a huge job in restoring trust but it shouldn't be written off. We see a good opportunity to buy the stock at current levels - more earnings bad news is unlikely and, remember, there is no debt issue, unlike many other cyclical businesses.
size/s: "[[[300,250],[300,250],[300,50]]]"
Set a stop-loss at around 85-90 cents. Residential real estate sales commissions are estimated at $5 billion a year. It's a huge market.
Get stories like this in our newsletters.
Related stories

Money Newsletter
size/s: "[[[300,600],[],[[300,600]]]]"
size/s: "[300,250]"